








Robert Chestnut
Medicare & Real Estate Advisor
190K+ Impressions
40+ Qualified Partner Conversations
577% Above Industry Standard
90+ Newsletter Subscribers
Last updated September 7th, 2026
Table of contents
Key Takeaways
If you couldn’t tell by his name, this is my dad.
When he first got into Medicare, he had less than 20 people in his book of business. He was only doing it part-time as an independent agent.
In 4 months we booked him 40+ conversations with financial advisors. Some of those partners have 3-4 decades of experience in their business, either as a principal, managing partner, retirement income planning, or managing director.
To give you a reference point, the industry average is 1-3 referral partners per year. We were able to surpass that average by 577% in 4 months.
No matter how much credibility you have in the Medicare space, any agent can do this; all we did was establish his current proof as a real estate agent, which he still does and has done for the past 26 years.
Lastly, we turned that current credibility on LinkedIn into his longest-lasting leverage point: a newsletter we built with over 90+ subscribers on that keeps bringing in referral partners over time without him having to hop on calls. The letter generates referral partners, retirees, pre-retirees, and people helping aging family members, so he spends less time and energy chasing leads.
Building
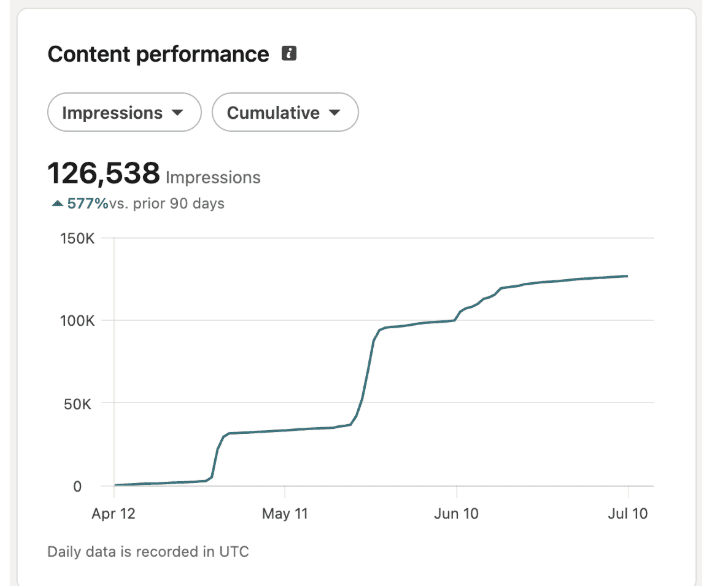
126,538
impressions in the last 90 days
+577%
vs. the 90 days before it
Here’s the problem we ran into first. No Medicare agent on LinkedIn was doing what we wanted to do for Rob. Nobody to study, nobody to steal from. So we looked at the next closest group instead, financial advisors. There are plenty of them on LinkedIn, and they happen to be the exact people we needed Rob in front of. We pulled from how they talked about themselves, and we built content that spoke straight to them.
What we actually posted
Personal content is what carried Rob the hardest. Twenty six years in real estate meant people already trusted him, especially locally. That kind of trust doesn’t come from a script. It comes from someone people recognize.
On the Medicare side, we built posts around real client scenarios. What a client could run into with their financial advisor if nobody caught it in time. Some came straight from Rob’s own conversations with clients. Some came from what was moving in the Medicare industry that month, since that world never sits still.
Turning posts into newsletter signups
About a third of his posts carried a call to action toward the newsletter. With this many impressions, there are always lurkers watching and never engaging. So we leaned into the real urgency already sitting in the room. People turning 65 every day. What happens to their advisor’s book if nobody flags the Medicare gap. What happens to the client if nobody does. Framed that way, joining a free newsletter isn’t a big ask. It’s an easy yes. Advisors could join through the post, or straight from his profile.
Every bit of it came from somewhere real. CMS data, Rob’s own client conversations, what was actually happening in the field. Nothing made up.
Qualifying

Most Medicare agents carry the same worries before they ever send a DM. Will a financial advisor even take me seriously? Most have dealt with an advisor who just wanted a lead swap, and that’s not how this relationship works. Some don’t even see LinkedIn as a real channel for this. Nobody wants to come across as a salesman. They just want to help their clients. Some worry the outreach will read as AI-generated the second an advisor opens it. And plenty doubt a stranger, or a bot, could ever sound like them well enough to represent them.
Here’s how we solved it for Rob
We never pitched anyone. Every conversation opened the same honest way, something like, “I don’t know if this makes sense for you, but do you work with clients who are pre-retirees or retirees?” That question ran in every outreach thread, over 200 of them, not a scripted lead-swap ask. We built rapport early too, bringing up where someone lived, how close it was to Rob, and small local details that made the message feel like it came from a real person in the area. And every word came from Rob’s own content and his own way of talking, pulled directly from the documents we built off of him.
Creating a financial advisor conversation database
We built this entirely off Rob’s actual LinkedIn conversations, over 200 real DM threads with financial advisors, the ones that turned into booked calls and the ones that didn’t. We pulled every single one apart: what worked, what killed the conversation, how long it took, and what the advisor said right before they agreed to a call.
That got organized into a knowledge base: a playbook broken into layers. One layer is how the advisor needs to perceive you: the psychology. Another is the actual message patterns that converted, broken out by scenario: cold outbound, someone who already has a Medicare guy, an experienced advisor who needs space instead of pressure, and so on. Another layer is just the small stuff: phrasing, timing, and when to send a voice message instead of text.
Then the AI reads a live conversation, figures out exactly where it’s stuck or what stage it’s at, and gives back two to four ready-to-send replies, grounded in what’s actually worked before, not a guess.
It wasn’t built in an afternoon. It’s the output of months of running outreach, logging every conversation into a tracking system, and refining the playbook every time a pattern showed up more than once. So when it tells you to ask “Do they loop you back in on the plan?” instead of arguing with “I already have someone.” That’s someone real. A guy named Walter booked a call the same day because of that exact question.
Nurturing
March 2026 to today
Mar
Apr
May
Jun
Jul
Aug
Sep
0 to 90+ subscribers since March 2026.
59% Open · 18% Click
Here’s what runs through most Medicare agents’ heads when they hear newsletter. Nobody reads those anymore. Another tool to manage. It won’t book meetings. It could take months to see anything. Someone has to be the one who finally asks for the referral, and they don’t even know what to offer in return. It feels passive, like it’s just sitting there doing nothing. Reaching out to people not even on the list feels like it dilutes the focus instead of building something real. And a partner who hasn’t sent a single referral yet probably isn’t going to start just because another email lands in their inbox. On top of all that, long-term maintenance becomes one more thing they’re personally on the hook for, and none of it feels like it compounds on its own.
Every one of those worries makes sense. None of them hold up.
Why the newsletter is the asset
The newsletter is the single greatest asset a Medicare agent can build. Financial advisors are not ignoring you out of spite. They’re not sending referrals because they genuinely don’t know when their client turns 65. That’s it. That’s the whole gap. So the newsletter is a touch point, the same job your content does, just quieter and more consistent. It keeps you on their mind for the one moment that actually matters.
And it’s not just for advisors. Every referral partner you’ve ever had, every client curious about what’s changing in Medicare, every prospect who isn’t ready yet, all of it goes on one list. That list takes the energy you’d normally spend chasing new outreach on LinkedIn and turns it into something that runs without you standing over it every day.
What it actually produces
The ones actually nurtured this way are the ones who eventually ask you to run a seminar with them. The ones who send you someone without ever needing a call first, because they’ve already seen enough proof to trust you. And on the client side, someone turning 65, or helping a parent through it, or retiring early, sees you covering the biggest changes in Medicare, pulled straight from real sources, and they sign up wanting to work with you before you ever reach out.
That’s the shift. You stop building a book of business that only grows with your effort, and you start building an asset that compounds on its own. Medicare runs on timing. Keeping people on a list until the moment they turn 65, or keeping a partner warm until they finally have someone to send you, is the smartest move a Medicare agent can make, at any book size.
Who’s On The List
23
15
12
26
24
Their Challenge
Rob was part-time. Less than 20 people in his book. No credibility in Medicare, starting from zero, and he knew it. He’d never had to put himself out there before, so the idea of going online scared him. Opening up wasn’t comfortable for him either. He worried about what he said getting used wrong, or taken out of his hands. He’d never built a referral partnership in this space in his life and had no idea what to say to a financial advisor if he actually got one on the phone. Then add the tools on top of it. Notion, dashboards, a newsletter he’d have to learn. He hated all of it before he even opened one.
Our Approach
Step 1: Deep dive.
We sat down with Rob first. Background, current business, goals. Twenty six years in real estate. He wasn’t the sharpest guy in the room, and that never mattered. What mattered was he’d spent decades walking people through the biggest financial decision of their life, buying a house. He didn’t need new credibility. He needed to bring the credibility he already had into Medicare.
Step 2: Understand the referral partner.
Before we touched his profile, we figured out what a financial advisor actually wants. It’s never about whether to send a referral. It’s whether the agent makes the advisor look good to his own client, or makes him look stupid. Handled wrong, that’s a risk to the advisor’s book. Handled right, it protects him from losing that client to someone who does everything. Rob didn’t just want leads. He wanted proof this could work starting from zero, and he needed it fast, since real estate was still his full time job.
Step 3: Build the ICP and set the goals.
Everything from steps one and two became Rob’s ideal customer profile. This was the backbone. Every step after this ran off of it.
Step 4: Content messaging.
We sorted his content into buckets. Authority, personal, growth, pattern interrupt, industry insight, lead gen. Then we mapped every financial advisor problem we knew of against those buckets. Every post got built out in Notion first, so Rob could see it and approve it before anything went live. He never had to learn a new tool. He just had to read what was already sitting there.
Step 5: Profile revamp.
Once the content direction was locked, we rebuilt his profile around it. The headline read helping Massachusetts retirees avoid Medicare mistakes. That one line told any financial advisor who visited his page that his interest was their client, not his commission.
Step 6: Launch and cadence.
Two to three posts a week, every week, pulled straight from biweekly thirty minute calls with Rob about what was actually happening for him, in real estate and in Medicare. We kept the real estate stories in on purpose. That was where his authority already lived, and it gave people a reason to trust him fast.
Step 7: Outreach and the newsletter, running in parallel.
DMs went out qualifying financial advisors, just checking if Medicare was even a gap for them. Rob had never built a referral partnership before this, so we handed him real recordings of how those conversations should go, and he never had to guess what to say. At the same time, the content was pulling in impressions from healthcare and finance. The newsletter caught everyone who was watching but not ready to talk, and kept every prospect and partner warm without another call. That list became the highest leverage thing we built for him. It only grows from here.
Before and After
Before
300+ LinkedIn followers
Decades of knowledge in real estate, but no time to turn it into content
No content output at all, and scared to put himself online
Less than 20 people in his book of business, with no idea how to grow it.
After
6 to 12 LinkedIn posts each month
Inbound referral partners from financial advisors, reaching pre-retirees and retirees
190,000+ impressions generated, 577% above industry average
40+ qualified partner conversations, 90+ newsletter signups
Went from no credibility in Medicare to a recognized name in Massachusetts, with 1,300+ LinkedIn followers
Top Content
The Posts That Made Financial Advisors Stop Scrolling.




Proof · The Partners
More referral partners already in.
Managing Director
Team of 4 advisors · MA, RI & CT
Already sending a referral before the first call even happened.
Private Wealth Advisor
25+ yrs
Retirement planning, estate strategies, and family finances — the same conversations that lead straight into a Medicare question.
President, Financial Planning Firm
20+ yrs
Came inbound off a single post. Zero cold outreach.
President, Wealth Management Firm
22 yrs
Also runs a national advisor network. Followed the content. One DM later, they set up coffee.
Founder, Wealth Advisory Firm
39 yrs
Joined the newsletter, then asked Rob to grab coffee.
Partner & EVP
32 yrs
Multi-year Five Star Wealth Manager. Reached out to Rob first, then introduced one of his own advisors.
